The Day Sovereignty Got an Interest Rate
This morning’s digest carried a number you rarely see in a sovereign story. SOFR plus 2.50 percent, 2030 maturity, $775 million. Those are the terms of the senior secured loan raised by the GPU cloud Nebius. The collateral is the running GPU infrastructure and, strikingly, customer contract cash flow. The money that runs the sovereign service arrived against customer usage, with an interest rate attached. This is the day sovereignty got an interest rate. So today I want to read this news not as technology claims but as contracts. Sovereign AI has crossed from the territory of policy and technology into the financing seat, and that is when the contract lens becomes the sharpest. In order: first the numbers of the terms, then the clauses, then the questions the buyer should ask.
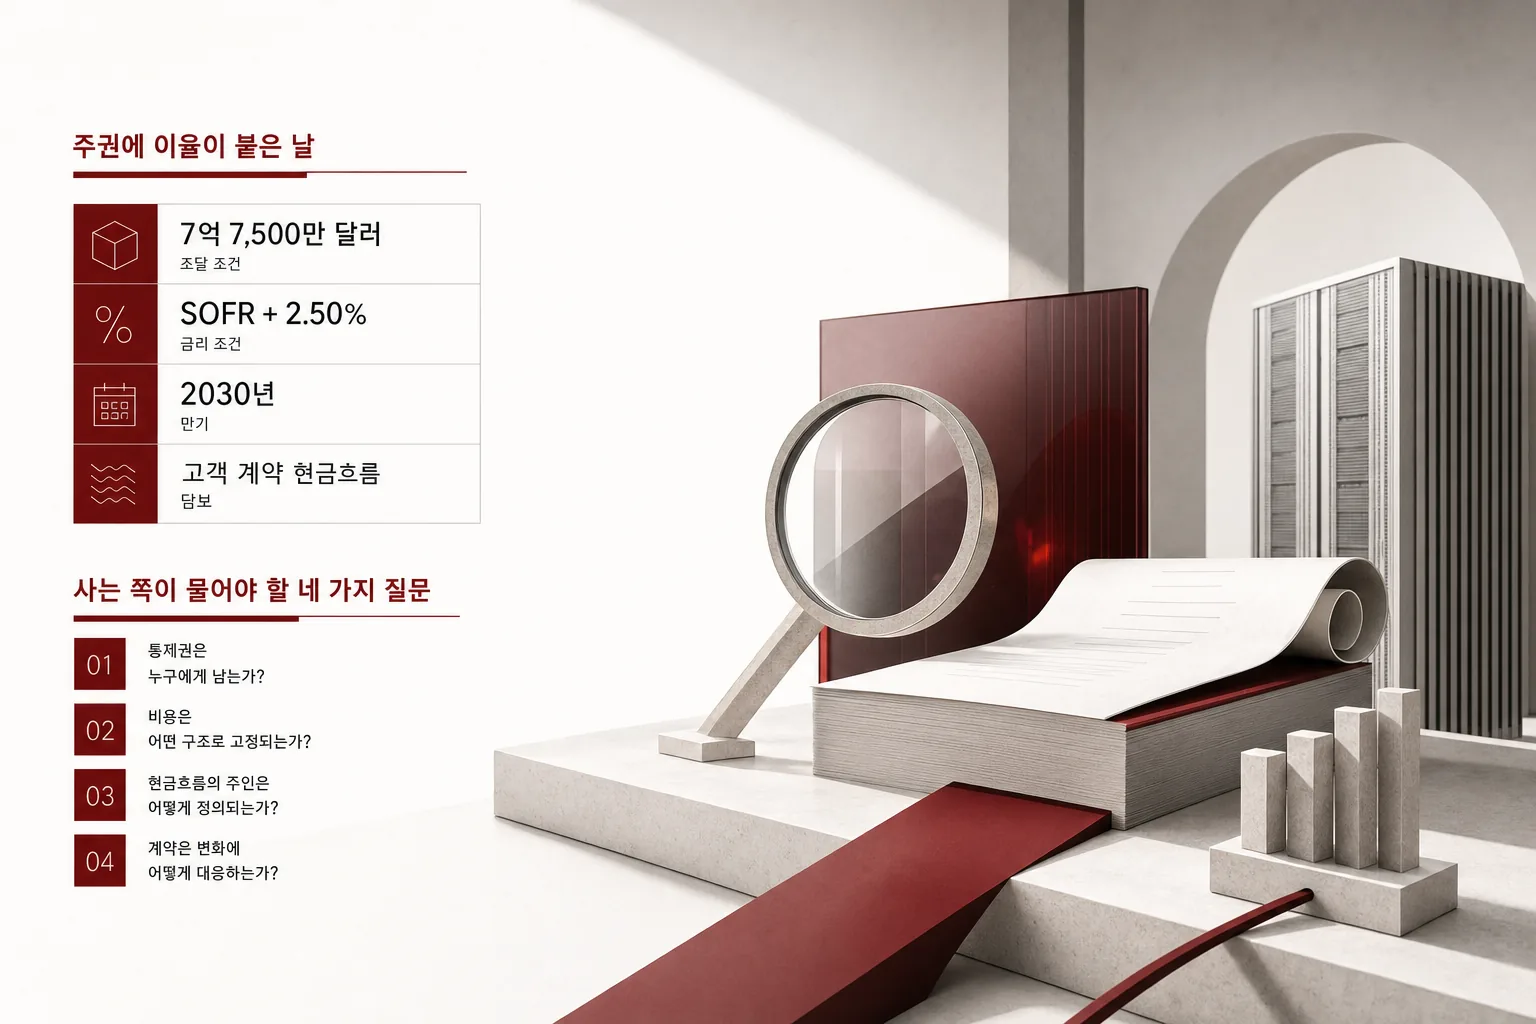 It visualizes the core concept of the article.
The Sovereign Wave: From Declaration to Contract
First, the wave. The sovereign AI articles in this week’s digest all point the same way: contracts, not declarations.
Japan is the clearest case. The major trading house Sumitomo Corporation has partnered with the domestic AI unicorn Sakana AI. The explicit rallying cry of the collaboration that will plant ‘Made in Japan’ AI is ‘getting off US AI dependence.’ Sakana’s front line is Fugu, its multi-agent orchestration AI. Fugu is reported to have recorded performance on par with top models such as Fable 5 and GPT-5.5. This deal shows one formula: a model company alone cannot make a market, and sovereign AI becomes commercially viable only when it combines with a trading house that holds capital and enterprise customer channels. It is evidence that sovereign AI has moved from policy declaration to a real investment deal.
Korea attached a European stage to the same wave. Naver, leading with the global AI factory plan of 1GW or more announced with Nvidia and Brookfield, proposed co-building an AI factory for European companies and startups on the occasion of the president’s visit to France. The stage was roundtables with local media, IT, energy, mobility, and finance CEOs, and the tie-in was Naver Webtoon’s French content business. CEO Choi Su-yeon raised three axes: global AI infrastructure, data sovereignty and industrial AI for security, cultural content. The evidence offered was not benchmark scores, but the experience of actually building industry-specialized AI while protecting data sovereignty. In finance, the Bank of Korea’s BOKI, in nuclear, Hy-NuRI from KEPCO Hydro and Nuclear Power. References run in environments isolated from external networks become the basis of sovereign contracts. In Europe, the moment has arrived when demand concentrates on sovereign AI that protects each country’s own data sovereignty. It is also a model in which domestic infrastructure and industry AX capability are exported as a national brand.
And at home, the domain where sovereign AI first moved into the base is security. The Ministry of Science and ICT’s cybersecurity-specialized AI foundation model development project starts this month. The Naver Cloud-led consortium of 30-plus participating institutions integrates and uses 830 TB of security data, including incident logs and threat intelligence. Concerns were raised at the same time that sensitive information from participating institutions could be exposed to other institutions, and the techniques cited as solutions are federated learning and secure computing, which use source data for AI development without exposing it. The backdrop of this project is a large-scale breach such as the Tving 39.54 million account leak. As the first large-scale domestic case of training AI through collaboration on sensitive data, the standards set here are expected to become the benchmark that spreads to finance, medical, and public AI.
Japan, France, domestic security. The common denominator of the three cases is data sovereignty. Yet the form is different. This time, all of it is being signed as contracts.
The structure of the three deals shares the same skeleton. Japan is a trading house combined with a domestic model, Naver is an AI factory combined with data sovereignty, and domestic security is a national project combined with a private consortium. In every case, the model itself is not the center of the deal. Channels, data, and governance structure are being sold as a package. That the value of sovereign AI is being assessed in units of execution and channels rather than of the model is the most common signal this week.
Reading the Contract: What the Numbers Say
The contract that needs the most precise reading is the Palantir and Nebius deal, is it not? Let us look first at what the customer gets. The customer tunes open models with its own data on top of Nebius’s compute and inference services. Permission management and environment isolation are the job of the Palantir stack, AIP and Ontology, Foundry, Apollo. On the surface it looks clean. The model is open, the data is yours, and your own platform manages the permissions. It is almost identical to what the industry has been calling ‘sovereign’ up to now. Technically, the answer seems already in hand.
But reading means something else. The fact that Nebius borrowed money with customer contract cash flow as collateral means that customer usage has become a financial asset. This loan is a senior secured loan maturing in 2030. The longer the maturity, the longer the payment commitment stays attached to the customer. When a supplier raises funds against its customers’ contract cash flow, the customer’s payment commitment becomes the lock-in device. The analysis points to three things: the possibility of committed price adjustments, switching costs, and service continuity. If usage falls or the customer changes suppliers, the payment commitment can remain as a cost burden on the customer’s side. The article’s judgment is clear. Control of data and models alone is not enough for sovereignty to be effective. The effectiveness of sovereignty is a function of the contract terms. Put alongside that: Palantir’s Q2 revenue grew 93 percent on ‘AI sovereignty’ demand. The side that sells sovereignty grows on that demand, and the side that buys it has to do the reading. Sovereignty now has a price list, and the price list has terms. The rise of power-secured sites and modular data centers as the standard formula for sovereign AI is the same context. The asking price of sovereignty is, in the end, a cost.
What this deal points to is that the sovereignty question is being rewritten from ‘whose model is it’ to ‘whose contract is it.’ That is not a product improvement. It is a change in the market’s frame.
And this reading carries straight over to the domestic contracting scene. In public, finance, and defense procurement, and in enterprise contracts, the point is raised that evaluation criteria must include not only data sovereignty but also switching costs, price adjustability, and continuity conditions. Contract design capability in AIDC procurement is emerging as a substantive competitive power. The eye that buys sovereignty must now become the eye that reads contract sentences.
The Buyer’s Four Questions
So what should the buyer ask? Four things.
First: when you cut usage or change suppliers, where does the payment commitment land. That is the lock-in question. If the answer to the lock-in question is ‘the customer pays,’ the sovereignty in the contract becomes an empty shell. Second: can the committed price be adjusted. That is the cost question. In a long-term contract, the presence of a price adjustment clause decides who carries the burden of cost increases. Third: what is the service continuity SLA. That is the operations question. When the service stops, whether you can take your data and models with you sets the weight of the SLA. Fourth: where are the data and the model, and who can see what. That is the sovereignty question itself.
These four questions are not a luxury. The using side is already prepared. Globally, OpenAI’s enterprise revenue has overtaken consumer revenue for the first time. The ARR of its enterprise business is estimated at roughly $40 billion. In Korea, ChatGPT’s enterprise usage grew 28x in a year. Business AI has even earned the label ‘the No. 1 hit of company welfare.’ At the same time, concerns about data leaving the country and sovereignty are growing alongside. ‘How do we govern business AI,’ permissions and audit, and cost control have emerged as the practical work of enterprise AI adoption. OpenAI Korea said the next-generation model Astra would be ‘something you feel the difference,’ and it is pushing an AI inference data center inside Korea and Stargate cooperation with Samsung and SK. Usage is already here. Governance is not.
At home, the pressure to close this gap is more concrete. The National Assembly Research Service named AI policy the No. 1 ICT issue in its ‘2026 National Audit Issue Analysis,’ with Dugpamo the first item to be inspected. The criticism is that the first and second evaluations of the five elite teams lean toward technology and performance, leaving little incentive to enter the market. The government’s plan to secure 260,000 high-performance GPUs needs up to 1GW of constant power at full operation, and the gap between the national grid’s headroom and the reality of local transmission and distribution is being raised as a problem. It also stands in contrast to the overseas example of Google signing a 22-year power supply contract with a Finnish nuclear plant. The AI talent program, tilted toward university support, made the same national audit issue list. Sovereignty is, in the end, verified at the execution layer: who runs it stably, and who leaves records that can be verified.
The Moment Sovereignty Becomes a Resource
The wave is clear. The unit of sovereignty is moving from ‘model ownership’ to ‘contract terms and execution environment.’ The four questions the buyer asks at this moment, permissions and audit, safe execution, cost control, become exactly what the platform must answer as a product.
ThakiCloud’s agent-native cloud Paxis comes in here. Paxis is a formally released product, and looked through today’s four-question lens, the design reads. In Paxis, skills, tools, policies, and audit logs are not after-the-fact features but first-class resources managed on equal footing. Policy as a resource means that sovereignty is written not as an appendix to the contract but inside the execution platform. Autonomy, too: the L0 to L3 governance and policy gates decide which agent performs which task, and every decision leaves an audit log. The answer to audit is not a report attached behind the contract but the record that execution produces. The answer to the fourth question, who can see what, is written into the permission structure.
Execution happens inside isolated sandboxes. That is the answer to the question of safe execution. MCP connectors and the skill market are the devices that open managed channels for an agent to meet external systems. Paxis also goes into the places where data cannot cross the organization’s boundary, with sovereign, on-prem Kubernetes deployment, ai-platform. It points in the same direction as references such as Hy-NuRI, run in environments isolated from external networks. And CostRouter picks the model that fits each task. The answer to switching costs and price adjustment lives here. If the model can change at the task level, the risk of being tied to a specific supplier’s financial structure is lowered structurally.
The day sovereignty got an interest rate, the question left for companies is simple. Who will you sign with. The wave of the deal is already here. Because what you look at when you sign is not just the contract sentences. You should be looking at whether the execution platform is answering the four questions.
References
This article was written by synthesizing the news below.
- Digital Times, Google to invest 20 trillion won in Finland, builds AI infrastructure including data centers
- AP News, Naver expands AI alliance in France, seeking 1GW factory and industry-specialized cooperation
- Maeil Business, ‘The No. 1 hit of company welfare is ChatGPT,’ enterprise users grew 28x in a year
- News Road, Palantir and Nebius ‘AI sovereignty’: the contract terms and switching costs that decide its effectiveness
- Global Economic, ‘The end of US AI dependence’: Japan’s Sumitomo joins hands with Sakana AI to plant ‘Made in Japan’ AI
- IT Chosun, Dugpamo that failed to break the market, GPUs blocked on power: will ‘AI policy’ be the core national audit issue?
- Money Today Broadcasting, ‘Must prevent private information leaks during security AI development cooperation’: what to do with 830 TB of data